
The work bonus in Belgium reduces the personal NSSO contribution of 13.07% for employees on low pay. Since 1 July 2026 a white-collar employee gets up to € 127.54 (part A) plus € 171.99 (part B) a month. In 2026 the work bonus already changed in January and March, then three more times: in April, July and September. Since 1 August 2026 the tax work bonus has been higher too.
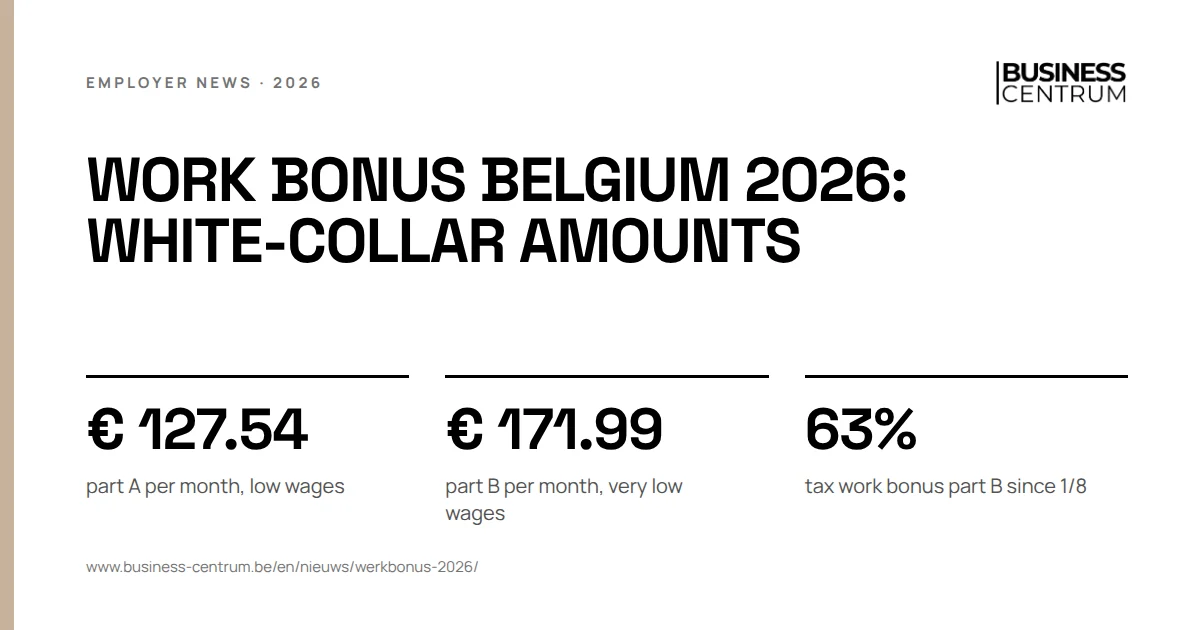
The 2026 work bonus: the April, July and September changes
| From | Part A white-collar | Part B white-collar | Why |
|---|---|---|---|
| 1 January 2026 | € 123 | € 165.87 | alignment with the January minimum wage; a correction of the part A ceiling followed on 1 March |
| 1 April 2026 | € 125.04 | € 168.62 | minimum wage increase |
| 1 July 2026 | € 127.54 | € 171.99 | indexation |
| 1 September 2026 | € 127.54 | € 171.99 | part A runs further, up to € 3,403.62 |
For blue-collar workers the amounts are higher because their contribution is calculated on 108% of pay: since 1 July € 137.74 and € 185.75, in April € 135.04 and € 182.11.
The April adjustment followed the increase in the minimum wage. What happened to the GGMMI is explained in our article on the minimum wage in Belgium in 2026.
How the NSSO calculates the work bonus in 2026
The NSSO calculates the work bonus per employee and per month, in three steps.
- Reference monthly wage (S). Gross pay for the month at 100%, also for blue-collar workers. The end-of-year bonus up to the amount of the reference monthly wage, single leaving holiday pay, severance pay, flexi pay and hospitality overtime do not count. For a part-time employee you convert pay to full-time.
- Basic amount (R). Part B is at its maximum up to a reference wage of € 2,300.62 and then falls by 0.27 per euro to zero at € 2,937.93. Part A is at its maximum up to € 2,937.93 and since September falls by 0.27 per euro to zero at € 3,403.62. In July and August that limit was still € 3,336.98, with a steeper phase-out of 0.32. Blue-collar workers have the same wage limits, with a phase-out of 0.29 for part B and, since September, 0.30 for part A.
- Reduction amount (P). For incomplete months or part-time work, the employee gets a share in proportion to the days or hours worked.
The work bonus can never exceed the personal contribution. If it does, you cut part B first, then part A. Per employee it is capped at € 3,594.36 per calendar year.
The work bonus in practice: what is the net gain?
The social work bonus per month for four employees on full-time pay:
| Employee | April | July | September | NSSO after work bonus, since July |
|---|---|---|---|---|
| White-collar on the minimum wage | € 286.21 | € 291.93 | € 291.93 | € 0 |
| White-collar, € 2,600 | € 200.68 | € 218.73 | € 218.73 | € 121.09 of € 339.82 |
| White-collar, € 3,200 | € 37.51 | € 43.78 | € 55.76 | € 362.48 of € 418.24 (September) |
| Blue-collar hospitality, category I | € 244.56 | € 264.05 | € 264.05 | € 89.48 of € 353.53 |
For the white-collar employee on the minimum wage (€ 2,233.61 since July), the work bonus wipes out the whole NSSO contribution. The hospitality worker earns € 15.21 an hour, or € 2,504.53 a month at 38 hours a week (38 x 52 / 12 hours). His NSSO is calculated on 108%, the work bonus on 100%.
The September change mainly helps wages between € 2,937.93 and € 3,403.62. For the white-collar employee on € 3,200 it brings € 11.98 a month more than in July.
Tax work bonus: 63% since 1 August
Part of the work bonus also reduces withholding tax: 33.14% of part A and, since 1 August 2026, 63% of part B. Until the end of July it was 52.54%. The increase comes from the royal decree of 24 July 2026, which already applies the personal income tax reform to withholding tax.
| Employee | Tax work bonus per month in July | Since August |
|---|---|---|
| White-collar on the minimum wage | € 128.64 | € 145.84 |
| White-collar, € 2,600 | € 90.18 | € 99.72 |
| Blue-collar hospitality, category I | € 112.01 | € 125.23 |
The reduction only applies as far as there is withholding tax to reduce. For the lowest wages it can therefore be smaller.
The 2026 work bonus on the payslip and in the NSSO return
On the payslip the employee sees a lower NSSO deduction: 13.07% minus the work bonus. The tax work bonus is built into the withholding tax. You calculate the work bonus every month and declare it each quarter in the DmfA as a reduction on the employee line.
If an employee takes holiday covered by leaving holiday pay, the personal contribution is sometimes too small to deduct the whole work bonus. You may carry the remainder forward to the next month. The end-of-year bonus does not increase the work bonus either: how to calculate it is in our guide to the end-of-year bonus. To see what a wage gives in net terms, use our gross-to-net calculator.
What Business Centrum does for you
Business Centrum automatically applies every new work bonus table in your payroll administration, together with Acerta, for white-collar and blue-collar staff, full-time and part-time. We check the annual cap and show clearly on the payslip what the work bonus brings the employee.