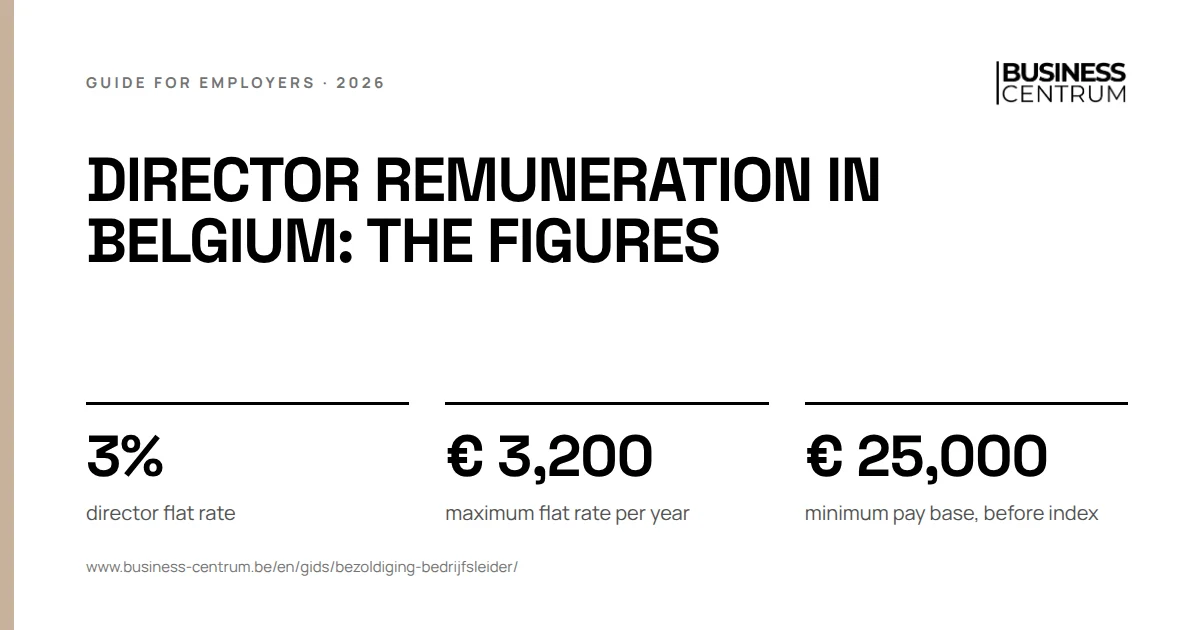
Director remuneration in Belgium is subject to withholding tax on the same scale as a salary, but with a much smaller flat-rate deduction for professional expenses: 3%, capped at € 3,200 a year. No NSSO contributions are deducted: the director pays social contributions as a self-employed person. From assessment year 2027, new rules govern the minimum remuneration.
This guide is for managing directors and board members of a small company who want to know what is deducted from their pay, and what the law of 15 July 2026 changed. What a director is in legal terms, with the mandate, liability and mixed situations, is on company director. Here we deal with the amount.
Director remuneration in Belgium: the same scale, a different flat rate
For withholding tax, the FPS Finance starts from the taxable annual amount. It deducts flat-rate professional expenses and applies the basic scale to what is left. The one big difference between an employee and a director lies in that flat rate.
| Employee | Company director | |
|---|---|---|
| Flat-rate professional expenses | 30% | 3% |
| Maximum flat rate per year | € 6,070 | € 3,200 |
| Maximum reached from an annual amount of | € 20,233.33 | € 106,666.67 |
| Social contributions | NSSO, employee share 13.07% | social insurance fund, as self-employed |
| Form for the annual pay | 281.10 | 281.20 |
On the annual amount after the flat rate, both use the same basic scale in 2026, with the 7% municipal tax already included:
| Band of the taxable annual amount | Rate |
|---|---|
| up to € 16,710 | 26.75% |
| up to € 29,500 | 42.80% |
| up to € 51,050 | 48.15% |
| above that | 53.50% |
From the basic tax, € 2,987.98 is then deducted: the tax on the tax-free allowance of € 11,170. Dependent children and other family charges give further reductions. How the scale and the reductions work together is explained in what is withholding tax. The changes that follow in January are in withholding tax 2027.
Director salary in Belgium: a worked example of the withholding tax
Anyone searching for "director gross to net" often lands on a calculator for employees. That calculator uses the wrong flat rate and deducts NSSO, so it gives a net amount that is too high. The example below puts the two flat rates side by side, on the same taxable amount.
Worked example
A managing director with a taxable pay of 4,000 euros a month
A fictitious managing director, single and without children, has a taxable remuneration of € 48,000 a year. Which social contributions and costs he deducts first is for his accountant to check; the example starts from the taxable amount. For comparison, we calculate the same amount with an employee's flat rate.
| Step | Director | With the employee flat rate |
|---|---|---|
| Taxable annual amount | € 48,000 | € 48,000 |
| Flat-rate professional expenses | minus € 1,440 (3%) | minus € 6,070 (maximum) |
| After the flat rate | € 46,560 | € 41,930 |
| Basic tax on the scale | € 18,158 | € 15,929 |
| Minus tax on the tax-free allowance | minus € 2,987.98 | minus € 2,987.98 |
| Withholding tax per year | € 15,170 | € 12,941 |
| Per month | € 1,264 | € 1,078 |
The basic tax is € 9,944.05 on the first € 29,500, plus 48.15% on the part above it. The director thus pays € 186 more withholding tax a month, or € 2,229 a year, only because of the smaller flat rate. Amounts are rounded to the euro. The example leaves out the reductions for family charges, and it concerns withholding tax: the final tax follows from the personal income tax return, where actual costs and social contributions count.
For an employee, 13.07% NSSO comes off the gross salary first, before the withholding tax. An employee's gross salary and a director's remuneration can therefore never be compared directly. The full route from gross to net for employees is in gross to net, with the gross net calculator. That calculator is built for employees, not for directors.
No NSSO, but self-employed social contributions
For social security, a company director is self-employed. He does not pay NSSO on his remuneration, but social contributions to a social insurance fund. These contributions are first calculated provisionally and later adjusted to the actual professional income.
| Part of the professional income (2026) | Contribution |
|---|---|
| up to € 75,024.54 | 20.50% |
| from € 75,024.54 to € 110,562.42 | 14.16% |
| above € 110,562.42 | no further contribution |
| Minimum as a main occupation | € 890.42 |
On top of this the fund charges management costs, which differ per fund. What a social secretariat does and does not do for a self-employed person is explained in social secretariat for the self-employed. If the director also genuinely works as an employee for his company, under someone's authority, NSSO applies to that part. The NSSO watches the line between the two statuses closely: see bogus self-employment.
Minimum director remuneration from assessment year 2027
A small company pays 20% corporate tax on the first € 100,000 of profit, instead of the standard rate of 25%. That reduced rate depends on the director's remuneration. The law of 15 July 2026 rewrote the condition, applicable from assessment year 2027.
| Condition | What the law says |
|---|---|
| Base amount | at least one director receives at least € 25,000, charged to the result of the taxable period |
| Indexation | adjusted every year to the consumer price index, rounded to a multiple of € 1,000 |
| New company | the condition only applies from taxable period 5 after incorporation |
| Remuneration below the minimum | the reduced rate stays, as long as the company's taxable income does not exceed the remuneration |
| Benefits in kind | no reduced rate if the flat-rate part exceeds 20% of total director remuneration |
The base amount of € 25,000 therefore does not apply as such: the indexed amount is what counts. At the time of writing, the FPS Finance has not yet published that amount for assessment year 2027 itself. Other sites already calculate it with a coefficient; we quote no amount until the FPS publishes it. Agree with your accountant which amount he uses for your financial year, and do it in time: the remuneration must be charged to that year's result.
The rule that lower is not automatically wrong matters for small companies. If you pay a remuneration below the minimum, the company keeps the reduced rate as long as its taxable income does not exceed that remuneration. Only when the profit is higher than what the director received does the reduced rate fall away for that year.
Benefits in kind: the new 20% limit
A company car, a home or a laptop from the company is a benefit in kind. It counts as remuneration, at a flat-rate value. From assessment year 2027, the law of 15 July 2026 sets two limits on it.
| Who | Limit | Consequence above the limit |
|---|---|---|
| Directors | the flat-rate part of benefits may not exceed 20% of total director remuneration | no reduced corporate tax rate |
| Employees | the flat-rate part of benefits may not exceed 20% of total employee remuneration | a separate tax of 7.50% on the excessive part |
Anyone who receives most of his remuneration in kind, with low pay in cash, puts the reduced rate at risk from 2027. How the benefit for a company car is calculated is in benefit in kind for a company car, with next year's changes in company car 2027. Other changes for next year are in what changes in 2027.
Director remuneration: form 281.20 and the returns
On the remuneration it pays, the company withholds tax and pays it over, just as for employees. Every year it prepares a form 281.20 for each director with the remuneration, the benefits in kind and the tax withheld.
| What | When | Where |
|---|---|---|
| Withholding tax return and payment | monthly or quarterly, depending on the amount | FinProf, with return 274 |
| Form 281.20 for 2026 remuneration | no later than 28 February 2027 | Belcotax-on-web |
| Form 281.10 for 2026 employee pay | no later than 28 February 2027 | Belcotax-on-web |
| Director's personal income tax return | in the year after the remuneration | Tax-on-web or through the accountant |
A missing or incorrect form is more than a formality: remuneration without a correct form can lead to a separate tax for the company. How the employee form works, and how form 281.20 differs, is in form 281.10.
Five mistakes with a director's remuneration
- Using an employee calculator. It uses a 30% flat rate and NSSO, and gives a net amount that is too high.
- Setting the remuneration only after the financial year. For the reduced rate it must be charged to that year's result.
- Paying everything in kind. From assessment year 2027, too large a share of benefits in kind costs the reduced rate.
- Copying an amount from an article. The indexed minimum depends on the assessment year; check it with your accountant.
- Forgetting form 281.20. It is separate from your employees' forms 281.10, but has the same deadline.
Remuneration and staff with Business Centrum and Acerta
Business Centrum is a social bureau in Ghent, founded in 2013, and a recognised partner of Acerta. We handle the employer side: the payroll, the Dimona declarations, the contracts and the leave of your staff. Acerta, recognised under number 250, files the declarations and collects the contributions. We weigh remuneration against dividend together with your accountant, as the company director page says. For a company with staff there is social secretariat for a BV, and how we work with Acerta is on social bureau and Acerta.
Want to look at your own remuneration and your staff's pay together? Request a call back and Business Centrum will review your situation with you and your accountant.