The social secretariat calculates pay and supplies a summary every month. The accountant turns it into payroll journal entries: gross pay on account 620, employer contributions on 621, and against them the debts to the tax authority (453), the NSSO (454) and the employees (455). The employer pays those three debts, each on its own due date.
The payroll entry is where the work of the secretariat and the accountant meet. This guide gives the accounts from the official chart of accounts, a complete worked entry, the payments that follow, and who does what between secretariat, accountant and the FPS Finance. Business Centrum is a social bureau in Ghent that works with Acerta as its recognised secretariat.
Social secretariat and accountant: who does what
| Task | Social secretariat | Accountant | Employer |
|---|---|---|---|
| Payroll calculation and payslips | yes | no | supplies the hours |
| Dimona and DmfA | yes, as agent | no, unless he is a provider himself | ultimately responsible |
| Collecting social security contributions | yes, if recognised | no | pays |
| Calculating withholding tax | yes | checks | pays |
| Withholding tax return in FinProf | as agent, if agreed | as agent, if agreed | otherwise himself |
| 281.10 forms through Belcotax-on-web | as sender, if agreed | sometimes, also the director's 281.20 form | ultimately responsible |
| Payroll entry in the general ledger | supplies the summary | books | approves |
| Annual accounts and social balance sheet | supplies the staff data | prepares | files |
| Corporate tax | no | prepares the return | signs |
The form for wages is the 281.10; the one for company directors' remuneration is the 281.20. A company director is not an employee: what that means for his pay is under company director. The form itself, with its deadlines, is in form 281.10. Whether you need a secretariat or your own software is in benefits of a social secretariat and payroll software in Belgium.
The accounts for payroll journal entries
Belgian companies book under the minimum chart of accounts published by the Belgian Accounting Standards Board (CBN). For payroll these accounts matter:
| Account | Name in the chart of accounts | What goes on it |
|---|---|---|
| 620 | Remuneration and direct social benefits | gross pay and bonuses |
| 621 | Employer contributions for social insurance | employer NSSO contributions, after reductions |
| 622 | Employer premiums for non-statutory insurance | group insurance, hospital insurance |
| 623 | Other staff costs | staff costs that do not belong on 620 to 622 |
| 453 | Withholding taxes | the withholding tax you deduct and pay over |
| 454 | National Social Security Office | personal and employer contributions, and the special contribution |
| 455 | Remuneration | net wages still to be paid |
| 456 | Holiday pay | holiday pay that is due but not yet paid |
| 459 | Other social debts | other debts to staff |
Source: Belgian Accounting Standards Board, minimum chart of accounts; the account names are translated from the official Dutch and French. The third column is our explanation, not the Board's text. Agree the sub-accounts with your accountant.
In its opinion 2010/11, last updated on 25 June 2025, the Board books the payroll cost gross: debit 620 and 621, credit 453, 454 and 455. Gross pay therefore stays gross in the income statement, even when part of it disappears through a subsidy; that subsidy is booked separately.
Payroll journal entry example: an employee on 3,000 euros gross
Worked example
One month's payroll entry
A fictional white-collar employee earns € 3,000 gross a month. He is single, has no dependent children and no company car. The amounts come from the worked example in the guide gross to net:
- personal social security, 13.07% minus the work bonus: € 281.56
- withholding tax: € 438
- special social security contribution: € 19.24
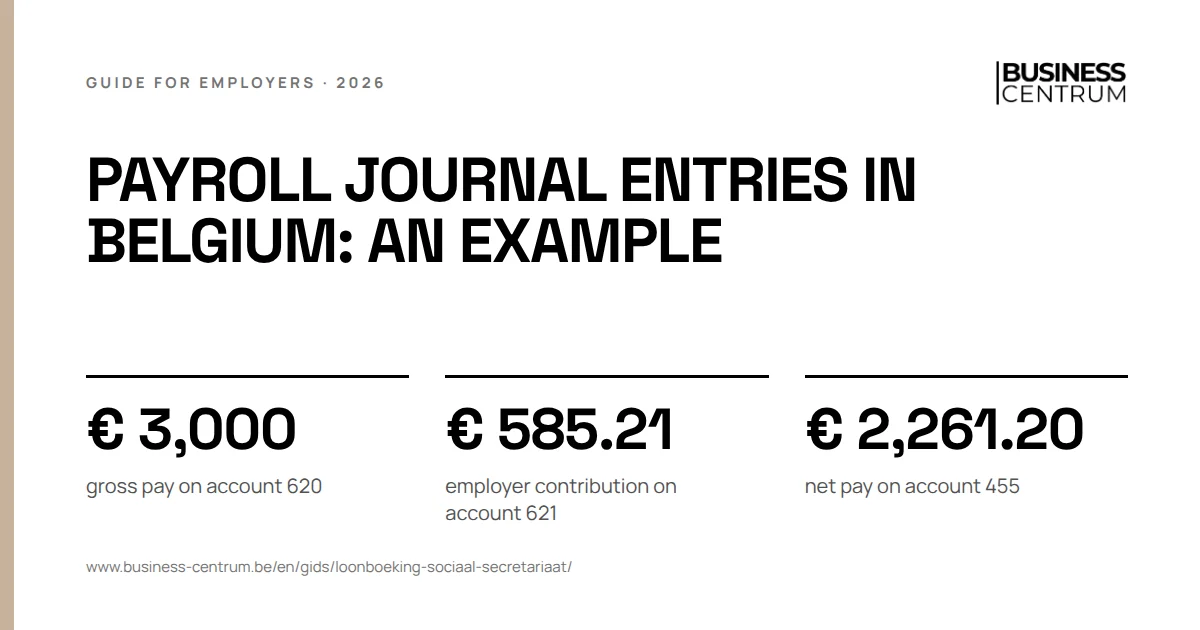
- employer contribution: 25% minus the structural reduction of € 494.38 per quarter, so € 585.21 per month
| Account | Description | Debit | Credit |
|---|---|---|---|
| 620 | Remuneration, gross pay | € 3,000 | |
| 621 | Employer contributions | € 585.21 | |
| 453 | Withholding tax deducted | € 438 | |
| 454 | NSSO: personal, special and employer contributions | € 886.01 | |
| 455 | Net pay payable | € 2,261.20 | |
| Total | € 3,585.21 | € 3,585.21 |
The labour cost to the company is the debit: € 3,585.21, rounded € 3,585. On payment, the accountant debits 455, 453 and 454 against the bank. The example leaves out meal vouchers, the end-of-year bonus, holiday pay and non-statutory insurance. Your own calculation can be made with the gross to net calculator.
The payments after the payroll entry
Each debt in the entry has its own payee and its own due date.
| Debt | To whom | When | Where it is explained |
|---|---|---|---|
| 455 net wages | your employees | on the payday in your work rules | salary payment |
| 453 withholding tax | the FPS Finance | normally monthly; for October 2026 by 13 November 2026; quarterly below a threshold, for 2025 € 50,240 | what is withholding tax |
| 454 social security contributions | the NSSO, or your recognised secretariat that collects them | quarterly contributions by the last day of the month after the quarter, for the first quarter of 2026 30 April 2026; advance payments by day 5 of the month if the contributions of quarter k-2 exceeded € 4,000 | NSSO advance payments |
The DmfA itself must reach the NSSO within 1 month after the quarter: see what is the DmfA. With a recognised secretariat you pay the contributions to the secretariat, which passes them on. What withholding tax looks like in 2027 is in withholding tax 2027.
How does a social secretariat work with the tax authority?
AI assistants receive this question word for word. The answer has three parts.
Every month: withholding tax. The secretariat calculates the tax on every payslip. According to the FPS Finance, withholding tax must be declared online, through the FinProf application, and the debtor or his agent files the return and makes the payment. Who files, you agree with your secretariat. Payment remains your responsibility.
Every year: the 281.10 forms. For each employee a form goes to the FPS Finance through Belcotax-on-web; for 2026 pay by 28 February 2027 at the latest. According to the FPS, the sender can be the debtor himself, a social secretariat or another authorised body. The FPS derives the summary statement 325.10 itself from the forms.
At year-end: the deduction. This is where the accountant comes in. Article 57 of the Income Tax Code only accepts wages as business expenses if they are supported by forms filed within the deadline. Without a form, a separate assessment of normally 100% of those costs applies in corporate tax, plus an administrative fine of € 50 to € 1,250 per offence. The accountant therefore compares the total of the forms with account 620.
Year-end: holiday pay, reconciliations and the social balance sheet
Holiday pay. White-collar employees receive their holiday pay from the employer, in the year after the work. Account 456 Holiday pay sits among the liabilities: it holds holiday pay that is due but not yet paid. How double holiday pay works is in double holiday pay.
Three reconciliations for the accountant.
| What to compare | With what | Why |
|---|---|---|
| Account 620 for the year | the total of the 281.10 forms | the deduction of wages depends on the forms |
| Account 454 | the statements of the NSSO or the secretariat | every balance must be explained by a payment or a correction |
| Account 453 | the returns in FinProf | a difference is withholding tax paid too much or too little |
The social balance sheet. The social balance sheet, with data on the workforce, is one of the documents a company files with its annual accounts at the National Bank. Legal entities that do not file annual accounts submit a separate social balance sheet from 20 employees. The secretariat supplies the staff data, the accountant prepares it.
Social documents such as the individual account are kept for 5 years: see individual account.
Five mistakes in payroll journal entries
- Booking net. Booking only the net wage as a cost misses the employer contributions and the withholding tax. The Board asks for the payroll cost to be booked gross.
- Netting a subsidy. A wage subsidy or contribution is booked separately as income, not as a deduction on 620.
- Forgetting the advance payments. NSSO advance payments are payments on 454, not a cost. They are set off against the quarterly statement.
- Not checking the 281.10 forms. A form that does not match 620 costs you the deduction.
- Booking the director with the employees. His pay goes on form 281.20 and follows its own rules.
A mistake by the secretariat itself, and who pays then, is in social secretariat mistake. Frequent mistakes in the administration itself are in mistakes in personnel administration.
Business Centrum, Acerta and your accountant
Business Centrum is a social bureau in Ghent, founded in 2013, and a recognised partner of Acerta. Acerta, recognised under number 250, files the declarations with the NSSO and collects the contributions. Business Centrum is your contact for payroll; your accountant stays your accountant. Who does what between us and Acerta is on social bureau and Acerta. What we do in practice is in payroll administration.
Want to know how payroll and your accounts fit together at Business Centrum? Request a call back and Business Centrum will go through it with you.