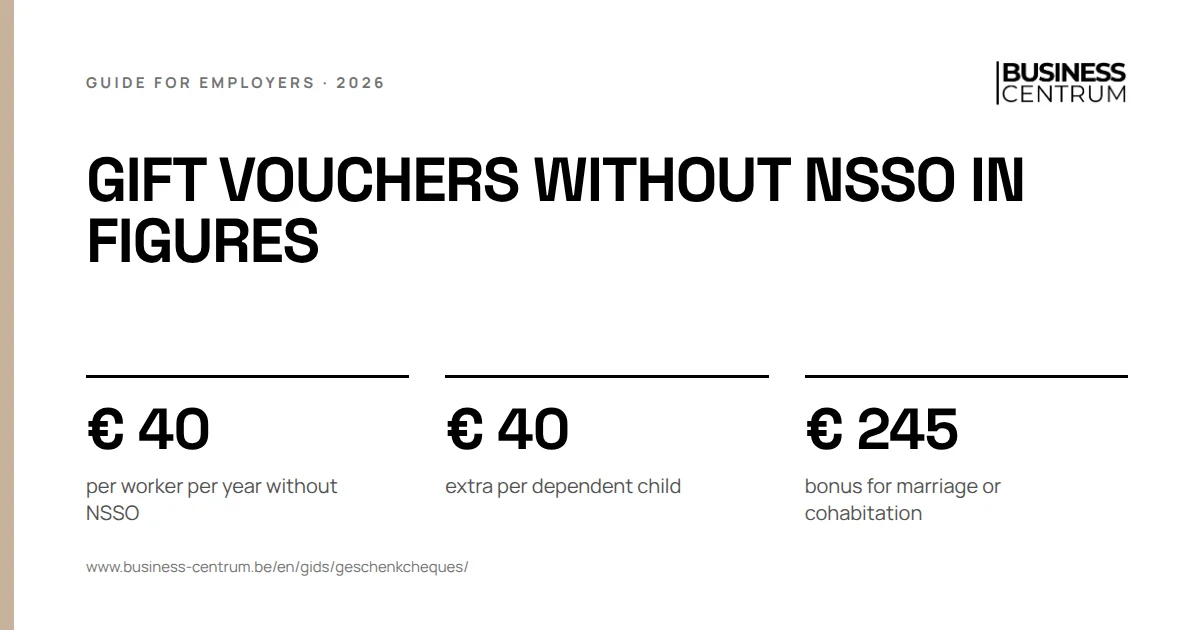
Gift vouchers for Saint Nicholas, Christmas or New Year are free of NSSO contributions up to € 40 per worker per year, plus € 40 per dependent child. The vouchers may not be paid out in cash and must have a limited validity. Above the limit you pay contributions on the full value, not only on the difference.
This guide is for the employer who wants to give staff a year end gift without it turning into pay. All limits come from the administrative instructions of the NSSO, the Belgian social security office. You read which occasions are exempt, how the NSSO judges your system, what going over costs and how to report the gift in the DmfA. What an ordinary bonus costs is in calculating the year end bonus.
What gift vouchers are and when they are not pay
A gift voucher is a shopping voucher your worker redeems at retailers that have an agreement with the issuer. For the NSSO, a gift in kind, in cash or in gift vouchers is in principle pay. There is an exception for three occasions: the year end holidays, an honorary award and retirement. On top of that, a marriage bonus up to a limit is not pay.
For gift vouchers three further conditions apply. They may only be redeemable at businesses that made an agreement with the issuer beforehand. They must have a limited validity. And they may not be paid to the worker in cash, in whole or in part. A voucher that does not meet these conditions is pay, even within the amounts.
| Condition for gift vouchers | What it means |
|---|---|
| Redeemable at affiliated businesses | the issuer has a prior agreement with the retailers |
| Limited validity | the voucher expires after a fixed period |
| No cash payment | not even in part, not even the balance |
| Within the amount for the occasion | per year and per worker, see the table below |
Gift vouchers are different from meal vouchers or eco vouchers. Those have their own rules: read meal vouchers employer contribution and what happens to eco vouchers.
The limits for gift vouchers per occasion
Each occasion has its own limit. The amount applies per worker and, for the year end holidays and the honorary award, per year.
| Occasion | Limit without NSSO | Special point |
|---|---|---|
| Saint Nicholas, Christmas or New Year | € 40 per worker, plus € 40 per dependent child | for the three holidays together, per year |
| Honorary award | € 120 per worker | only an official award outside the company |
| Retirement | € 40 per year of service with you | total value between € 120 and € 1,000 |
| Marriage or legal cohabitation | € 245 | contributions only on the difference above the limit |
A child is dependent on your worker if the worker actually bears all or part of the cost. An honorary award is an official or civil distinction granted outside the company, such as a decoration, an order of knighthood or the title of laureate of labour. Recognition for a company anniversary, for example 20 years of service, does not count as an honorary award. For such an anniversary there is the seniority bonus with its own limits.
Gift vouchers: the NSSO judges your system
The NSSO does not look at the amount each worker receives, but at the system you use to grant the gifts. This is the rule employers forget most often. If you give all your workers the same gift of € 100, all those gifts are pay. Even for workers with two or more dependent children, for whom € 100 would stay within their own limit.
If you want to give more to those with dependent children, your system itself must say so: a base amount per worker and an amount per child. Ask your workers beforehand how many dependent children they have and keep it in your payroll records. A spontaneous benefit at a special event can be a gratuity; more on that below.
Worked example: gift vouchers for four workers
Worked example
The same budget, two systems
A fictional small business has four workers. Anna has no children, Bram has one dependent child, Chloé two and Daan three. The manager wants to hand out € 400 in gift vouchers for Christmas.
| Worker | System A: € 40 plus € 40 per child | System B: the same for everyone |
|---|---|---|
| Anna, no children | € 40 | € 100 |
| Bram, one child | € 80 | € 100 |
| Chloé, two children | € 120 | € 100 |
| Daan, three children | € 160 | € 100 |
| Total gift vouchers | € 400 | € 400 |
| Employer contribution, 25% | € 0 | € 100 |
| Personal contribution, 13.07% | € 0 | € 52.28 |
In system A every worker stays within their own limit: no pay, no contributions. In system B the gift is pay for everyone, even for Chloé and Daan. The business then pays € 100 in employer contributions, and on each voucher of € 100 the worker loses € 13.07 in personal contribution. Payroll tax comes on top. The employer contribution here uses the base contribution including wage moderation, in category 1, without special contributions.
With the same budget you are better off choosing the system the NSSO exempts. What contributions on pay cost in general is in NSSO employer contribution. How a gross amount ends up as net pay for your worker, work out with the gross to net calculator.
Gift vouchers at retirement and marriage
On retirement the limit depends on the years of service with you: € 40 per year of service, with a total value between € 120 and € 1,000. A worker with 15 years of service can receive a gift of € 600. After 30 years of service the sum would come to € 1,200, but the maximum stays € 1,000. If you give more, the full value is pay.
The marriage bonus works differently. On marriage or legal cohabitation, a bonus up to € 245 is not pay, in cash, as a gift or in gift vouchers. If you go over that limit, contributions are due on the difference only. For a bonus of € 300 that is € 55: € 13.75 employer contribution and € 7.19 personal contribution.
Gift vouchers above the limit: how to report them
If a gift does not meet the conditions, you report it in the DmfA, the quarterly return to the NSSO. The pay code depends on how you grant the gift.
| Situation | Pay code in the DmfA | Quarter |
|---|---|---|
| Gift within the limit and the conditions | not reported as pay | |
| Gift unrelated to days worked, such as a Christmas gift for everyone | pay code 2 | usually the quarter of payment |
| Gift in proportion to the days actually worked in the quarter | pay code 1 | the quarter of the work |
| Marriage bonus above € 245 | the difference as pay | quarter of payment |
A Christmas gift that becomes pay raises the wage of the fourth quarter. That has a second effect: the structural reduction is calculated on that higher quarterly wage and goes down. The year end bonus is also under pay code 2 in the same quarter.
Gift vouchers, gratuities and other benefits
Besides the fixed occasions, the NSSO knows the gratuity: a benefit that is not pay because it has no link to the work. It must be something you grant spontaneously on a special event, in the company or in the worker's personal life, such as a company anniversary or a serious fire at the worker's home. There may be no tradition in your company of granting such a benefit, and the worker can claim no right to it.
| Benefit | When it is not pay | Read more |
|---|---|---|
| Year end gift vouchers | within € 40 plus € 40 per child | this guide |
| Gratuity | spontaneous, special event, no tradition | this guide |
| Profit bonus | its own scheme | profit bonus |
| Non recurring bonus | its own scheme via collective agreement | CAO 90 bonus |
| Choice between benefits | its own scheme | cafeteria plan |
An annual Christmas gift is therefore not a gratuity: it is a tradition, and the year end limits apply. If you want to give more budget per worker, look at a bonus or a plan with its own rules.
Gift vouchers for the company director and the tax side
The NSSO limits in this guide apply to employees. A company director is self employed and does not fall under the NSSO for employees. What a gift or voucher means for the director depends on the director's pay: read director's remuneration and the page on the managing director.
The tax side is separate from the NSSO. The NSSO instructions do not say whether the gift is tax free for the worker, nor whether you deduct the cost as employer. Have it confirmed for your company before you order the vouchers. If you want to grant a higher amount than a gift allows, work out what it costs as pay with calculating wage costs.
Five mistakes with gift vouchers
- Giving everyone the same amount above the base limit. The NSSO judges the system. A fixed amount of € 100 for everyone is pay for everyone.
- Counting the limit per holiday. The € 40 applies to Saint Nicholas, Christmas and New Year together, per year.
- A voucher that can be cashed in. A voucher the worker can turn into cash, in whole or in part, is pay.
- Treating an anniversary as an honorary award. Recognition for years of service in the company does not fall under the € 120 limit.
- Not capping the retirement gift. Even after a long career the maximum stays € 1,000. Above it, the whole gift is pay. The list of limits is also on our figures page.
Gift vouchers with Business Centrum and Acerta
Business Centrum is a social bureau in Ghent, founded in 2013, and a recognised partner of Acerta. We handle the employer side: the wages, the Dimona, the contracts and the leave of your staff. Acerta, recognised under number 250, files the returns and collects the contributions. A gift that becomes pay goes into the DmfA the secretariat files every quarter. How it works with payroll for one employee or for a small business, see those pages; how we work with Acerta is on social bureau Acerta.
Want to know what gift you can give your staff this year without contributions? Request a call back and Business Centrum sets up the system with you.